


 Claim Ownership
The Retirement and IRA Show
Subscribed: 790Played: 89,409
Subscribe

Description
What do you get when you combine two knowledgeable CFP® PROFESSIONALS (one also a well-informed COLLEGE FINANCE INSTRUCTOR)? If you mix in relevant financial information and a healthy dose of humor you get the Retirement and IRA Radio Show! JIM SAULNIER, a CERTIFIED FINANCIAL PLANNER™ Professional with Jim Saulnier and Associates who specializes in retirement planning for clients across the country, CHRIS STEIN, a Finance Instructor at Colorado State University who is also a CERTIFIED FINANCIAL PLANNER™ Professional, offer real-world knowledge on a diverse range of topics including Social Security planning, investing for your retirement, the fundamentals of 401(k) and IRA accounts. Jim and Chris make learning about your retirement both educational and entertaining!
667 Episodes
Reverse
If you would prefer not to learn about Jim’s upcoming drive to Ohio and the family change of plans also sending him to Massachusetts, you can skip to (10:00).
Chris’s Summary
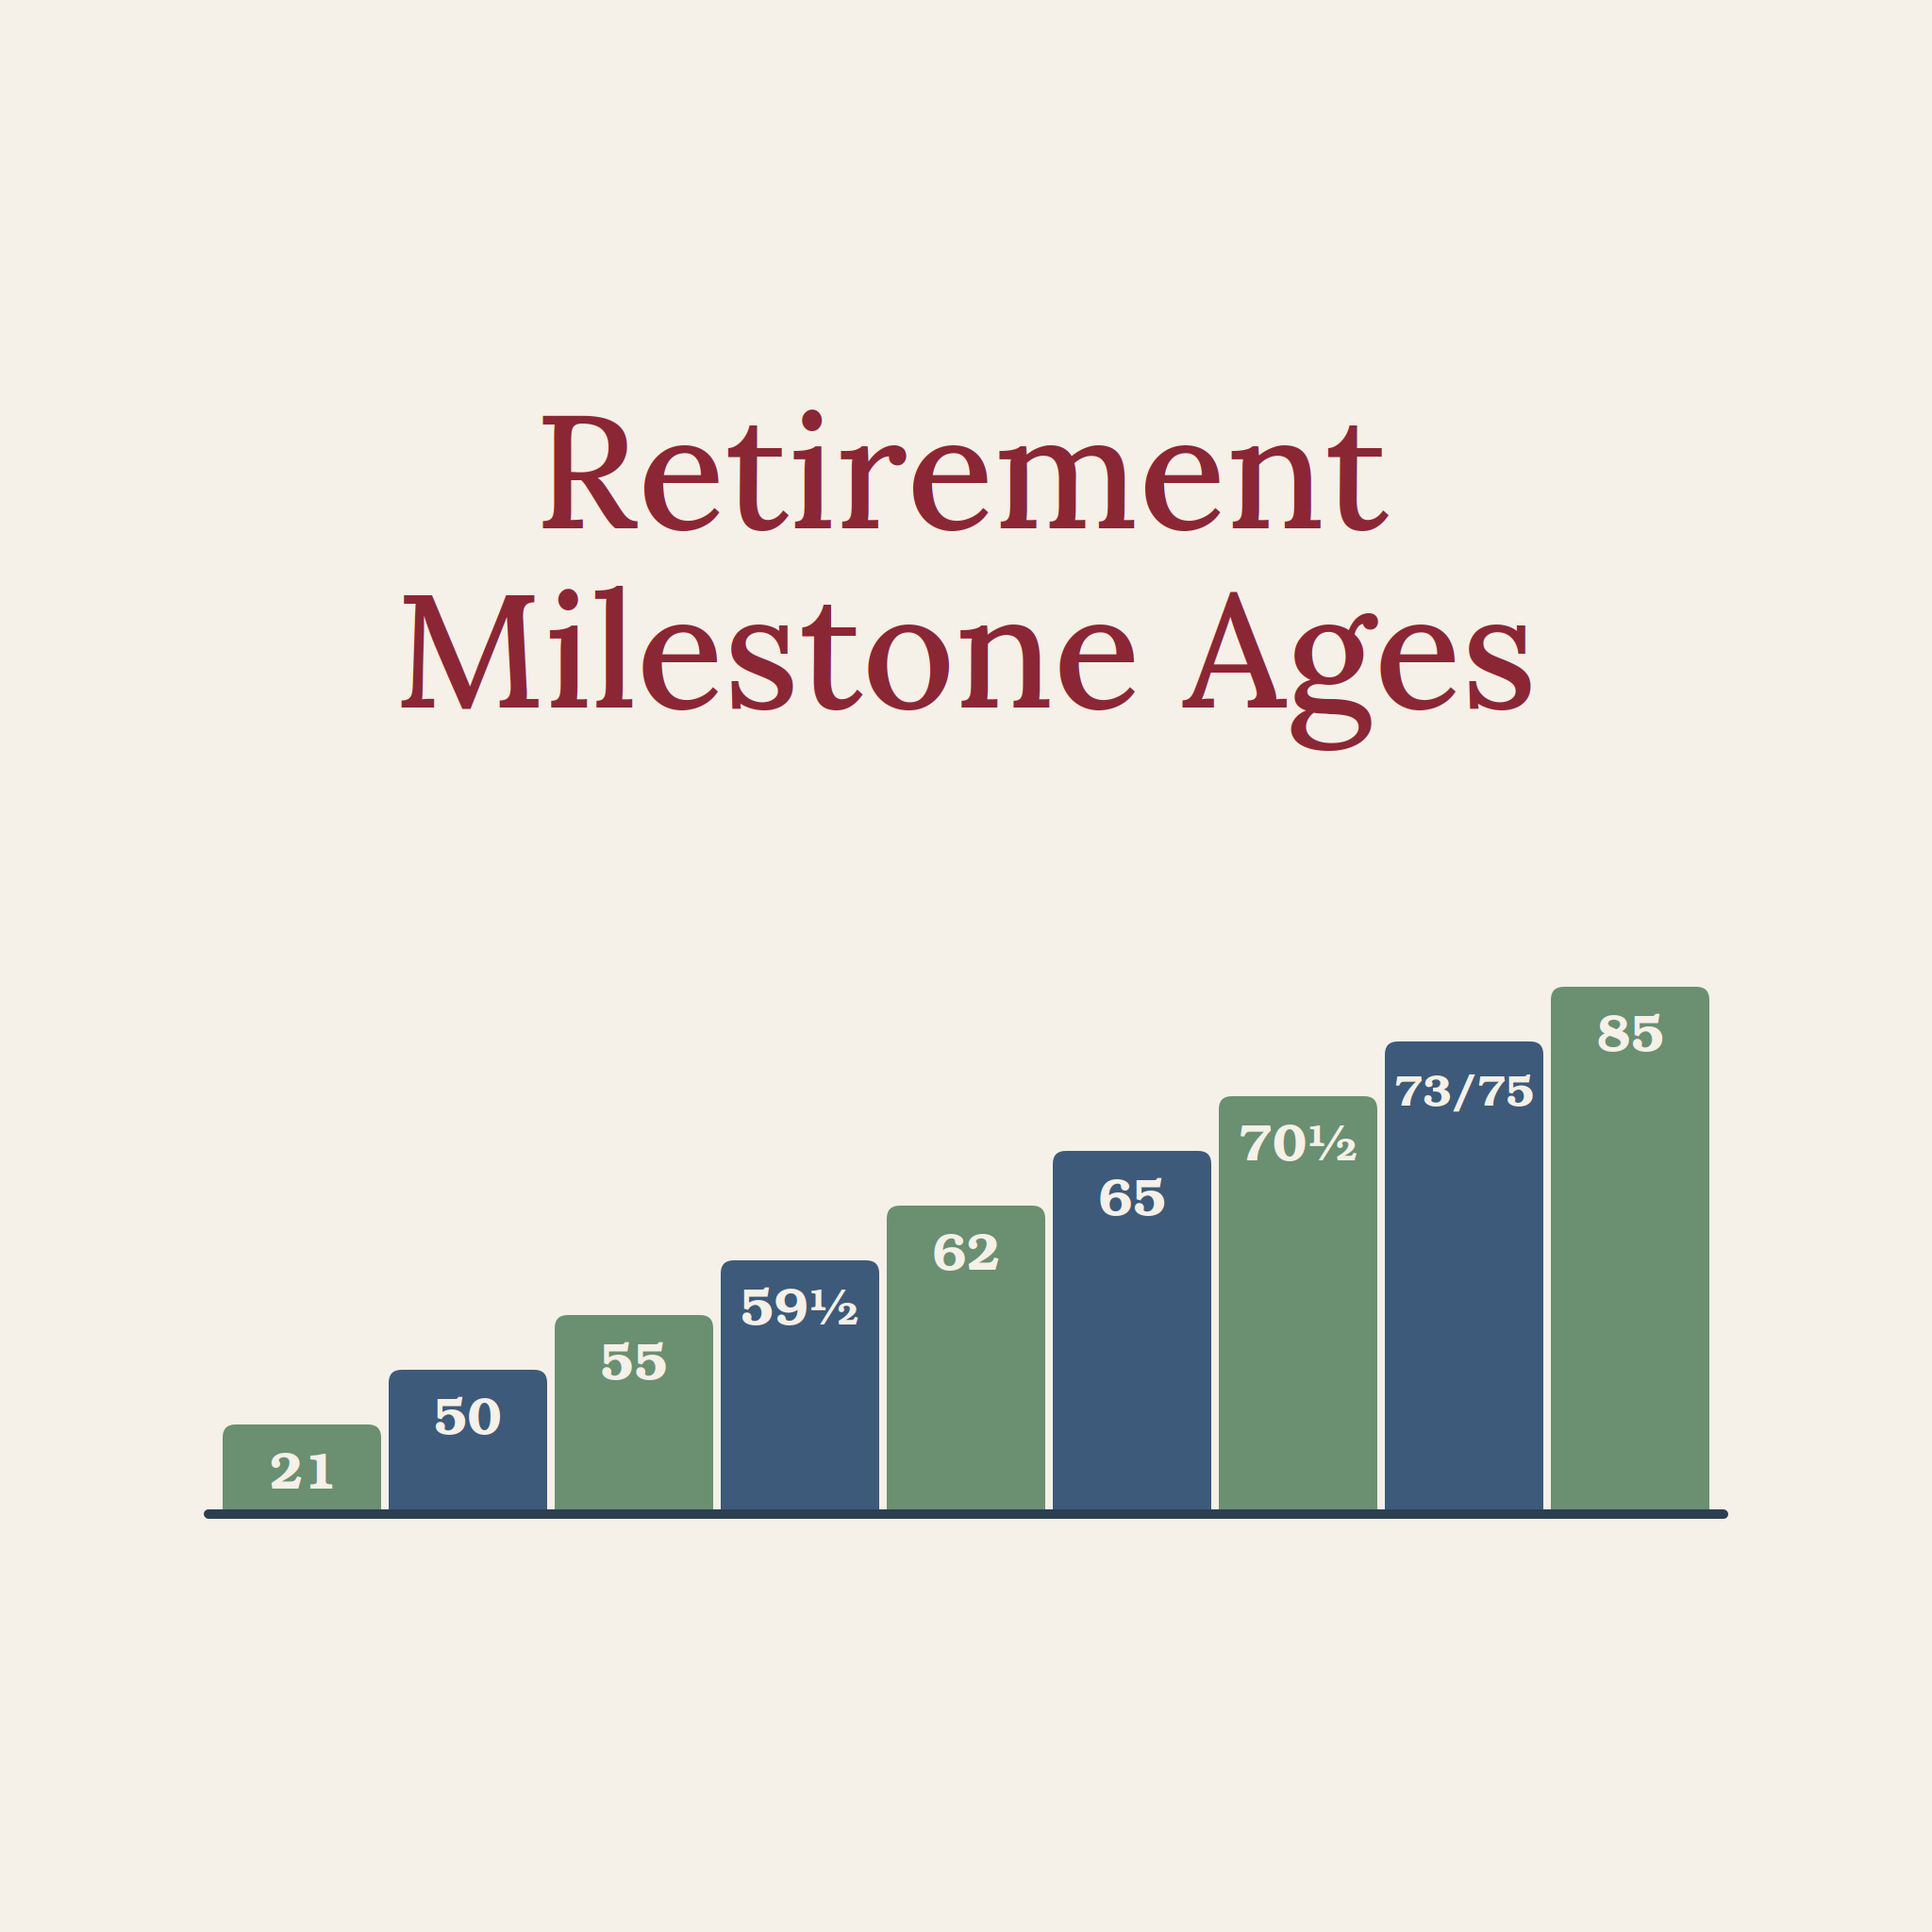
Jim and I walk through retirement milestone ages, from age 21, when a minor child beneficiary’s stretch gives way to the 10-year rule, through catch-up contributions, penalty-free withdrawal ages, Social Security survivor and retirement claiming ages, the IRMAA lookback at 63, Medicare at 65, QCDs at 70½, and RMDs at 73 or 75. We also cover an obscure age 75 RMD rule for pre-1987 403(b) contributions and the age 85 limit for starting a QLAC.
Jim’s “Pithy” Summary
Chris and I work through a list of retirement milestone ages I’ve been holding onto for a while, and the first stop, age 21, is a deep one. Folks, the stretch IRA is the Black Knight from Monty Python and the Holy Grail. It’s gravely wounded, but it’s not gone. A minor child of the deceased IRA owner, an eligible designated beneficiary, or as I call it, an eligible human, can still stretch until 21. Then the 10-year rule applies, and Chris and I guessed wrong on what happens next. I checked with the Ed Slott Group, and the answer comes down to one phrase: at least as rapidly.
Then we hit catch-up contributions at 50, including a new Roth rule this year that some listeners call a loophole. I don’t. We cover the carve-out that lets public safety employees skip the 10% early withdrawal penalty at 50, and the rule of 55, including a strategy the IRS has implicitly blessed. And then there’s the super catch-up. Folks, I have no idea what Congress was thinking. An extra $3,250 a year in your 60s is not going to fix anybody’s retirement. Let people in their 20s and 30s put more in, where it can compound. Chris brings in the Social Security and IRMAA ages, including a disabled surviving spouse rule that taught both of us something new.
At 70½, QCDs can help at the margins when a big RMD threatens an IRMAA tier. I make Chris guess an obscure age 75 rule tied to 403s, and he earns a B+. Then he pulls out one I totally missed at 85: QLACs. I give Treasury credit here, not Congress, and I explain why we’re a little softer on QLACs than on other deferred income annuities.
The post Retirement Milestone Ages: EDU #2639 appeared first on The Retirement and IRA Show.
Jim and Chris discuss listener emails on the best month to claim Social Security, IRMAA strategy for married couples, Social Security ex-spouse benefits, inflation and annuity purchase decisions for a Minimum Dignity Floor shortfall, and Minimum Dignity Floor tax calculations.
(9:30) A listener asks whether there is a best month to apply for Social Security benefits before age 70, given how often benefits are recalculated.
(20:00) George wants to know whether the SSA-44 IRMAA strategy applies to married couples filing jointly, and whether a spouse delaying retirement until mid-January would allow a large Roth conversion that year without that conversion triggering IRMAA later.
(29:30) The guys are asked to clarify ex-spouse benefit figures a Social Security agent gave a listener’s sister-in-law, including whether she can claim spousal benefits without starting her own and whether the numbers indicate she was the higher earner.
(47:30) Jim and Chris field a question on how to account for future inflation when making an annuity purchase to cover a Minimum Dignity Floor shortfall.
(1:10:30) A final email wonders why the Minimum Dignity Floor calculation doesn’t simply account for the taxes owed on that income separate from Fun Number spending.
The post Social Security, IRMAA, Annuity Purchase, MDF Calculations: Q&A #2639 appeared first on The Retirement and IRA Show.
Chris’s Summary
Jim and I use a Life Annuity Specialist article on pension risk transfer mortality models to examine longevity risk for individual retirees. These models weigh sub-ZIP codes, income, and over 200 socioeconomic factors, suggesting some retirees may live more than 10 years past age-65 life expectancy. We discuss why a household is a risk pool of one, why projections should reach well into the 90s, and why advocacy matters as the tax planning window closes.
Jim’s “Pithy” Summary
Chris and I dig into an article from Life Annuity Specialist, and no, this is not an annuity discussion. It covers a new approach to mortality tables that a consulting firm built to help insurers price pension risk transfers, and I’m not a fan of those, as you know. What amazed me was how granular it gets: sub-ZIP codes, pension size, blue-collar versus white-collar, and a model trained on millions of life years of data.
Here’s the thing, folks. The subset of the population this model says will live longer is pretty much those of you listening to this podcast. You VGers, you do-it-yourselfers, you’re more likely to have taken care of your health and followed what Dr. Phillip Snider shares about healthspan, not just lifespan. These risk tables let insurance companies handle that uncertainty because they’re spreading it across thousands of people, so no single long life throws them off. You don’t get that luxury. You’re a risk pool of one, a zebra on the Serengeti trying to survive outside the herd. You can pool longevity and cash flow through an annuity if you want, but you cannot pool your cognitive ability or your ability to avoid fraud.
Whether or not you ever buy a lifetime stream of guaranteed income to protect your Minimum Dignity Floor, that’s up to you. What we talk about in this episode is longevity risk that goes beyond outliving your money. Who is going to advocate for you at 85, 90, 95? Who updates your power of attorney, checks your beneficiaries, and looks out for the surviving spouse who was never into this stuff? As the tax planning window closes, the need for advocacy grows, and many of you are going to live a lot longer than you think.
The post Longevity Risk Beyond Money: EDU # 2638 appeared first on The Retirement and IRA Show.
Chris and Jacob discuss listener emails on Social Security survivor benefits, a TIPS ladder paired with a QLAC, investment positioning across taxable, tax deferred, and tax-free accounts, and buffered ETFs for sequence of returns risk.
(12:30) A listener whose spouse recently died asks whether they can claim child in care survivor benefits now while caring for their young daughter, and whether claiming now would affect their own survivor benefit at full retirement age.
(25:00) George asks for feedback on a TIPS ladder that runs only to age 79, with an extra amount set aside at 75 to buy a QLAC that begins paying at 80 and covers the Minimum Dignity Floor from there.
(48:15) The guys take a question on how to position a $2.8 million portfolio split evenly between taxable, tax deferred, and tax free accounts when funding spending and weighing tax implications.
(1:05:15) Chris and Jacob respond to a question about using buffered ETFs to help manage sequence of returns risk.
The post Social Security, TIPS Ladder, Investment Positioning, Buffered ETFs: Q&A #2638 appeared first on The Retirement and IRA Show.
Chris’s Summary
Jim and I discuss five common power of attorney mistakes flagged in an estate planning attorney’s article, along with points from Peter Scott. We cover naming an alternative agent, the friction a springing agency can create, gifting authority that is either absent or overly broad, notifying old agents and financial institutions after a change, and the boilerplate real estate language that title companies may refuse to accept.
Jim’s “Pithy” Summary
Chris and I go through an article timestamped December 2022, one of the 72 sitting in my iPad folder, where an estate planning attorney lists her five biggest mistakes to avoid with a financial power of attorney. I’m not an attorney, nor do I play one on TV, but I’ve been in this industry 27 going on 28 years and we deal with these forms quite often. I read her five, opine on them, and Chris weighs in after each. I also bring in Peter Scott, who shared with us on this show before he retired, because Pete flagged two of these as the big ones.
Her list covers backup agents, springing powers, gifting authority, changing agents, and real estate. I used to be a fan of springing powers. I’m not anymore, and it was Pete who turned me around on it. I had never thought of it that way before. Gifting is the one I think gets overlooked most, and I use my own mother’s document to explain why, because what wasn’t in hers had me beside myself. It involved my sister, my niece and nephew, and a lot of college tuition. Chris adds that locking a document down too tightly can backfire just as badly, and suggests what to do with wishes that don’t fit into legal language.
We also get into why banks and financial institutions often refuse older forms, the Colorado law Pete said he could fly a 747 through, and two clients whose documents came from the exact same software, where one attorney took the time to do the job and the other just clicked print. Pete’s warning on real estate was about boilerplate language, and Chris explains why the address you use every day may not be the one that matters.
The post Power of Attorney Mistakes: EDU #2637 appeared first on The Retirement and IRA Show.

Comments

Download from Google Play

Download from App Store
 United States