


 Claim Ownership
Uranium Unleashed Podcast
Subscribed: 0Played: 2
Subscribe

© Uranium Unleashed
Description
Strategic intelligence on global uranium and copper markets—institutional-grade insights on project development, industry catalysts, and market dynamics from over 20 years of international mineral exploration experience
uraniumunleashed.substack.com
uraniumunleashed.substack.com
84 Episodes
Reverse

Episode Overview This week brings an unusually dense collision of major corporate catalysts, geopolitical shifts, and price-confirmation milestones across the nuclear fuel sector. As uranium tests a $90 per pound spot price floor, hosts Alex and Jamie walk through the hard calendar, unconfirmed market developments, geopolitical friction points, and an unscheduled $50 billion wild card that could re-rate the nuclear equity complex.Key Topics Covered:Kazatomprom’s Shareholder Vote (Monday, Sept 22): Absentee voting opens on ratifying long-term uranium concentrate supply agreements with China’s SNURDC and Rosatom-affiliated Uranium One Group. The hosts analyze how ratifying these contracts locks up volume away from Western utilities, alongside a pending board vote to replace Yelzhas Otynshiyev with Zhandos Kairgeldi.Uranium Energy Corp Q4 Earnings (Sept 23–24): UEC posts full-year fiscal 2026 financial results, featuring the first full-quarter contribution from the Burke Hollow ISR facility and Christensen Ranch header house operations. Key focus areas include Q4 production, realized selling prices versus spot, and FY2027 production guidance against analyst consensus of ~($0.04) EPS on ~$9 million revenue.Testing the $90 Spot Floor (Friday, Sept 26): TradeTech prints its weekly spot price indicator following the September 11 close of $90 per pound. The hosts examine whether a second post-WNA Symposium close at or above $90 establishes a durable market floor.High-Probability Expected Developments:Bannerman Energy / CNNC JV: Formal execution window for the $321.5 million joint venture on the 67 million pound Etango project in Namibia following condition satisfactions on September 9.Post-WNA Utility Contracting: Anticipated RFP disclosures from major producers following 3 to 4 material requests for proposals flagged at the conference, with term indicators holding at $97 per pound.NexGen Energy & BHP Financing: Ongoing dialogue regarding $1 billion in funding over 9 months for the Rook I project amidst share price pressure.Geopolitical Radar & Sahel Friction:Global Atomic’s Dasa Project: The US DFC’s approval of a $414.2 million financing package in Niger, subject to three unmet conditions: an open export corridor (Cotonou closed since 2023 coup), mining permit extension, and an agreement with the military junta currently in ICSID arbitration with Orano.US Sanctions Legislation: US House passage of sanctions targeting Russian energy interests, putting Rosatom affiliate Uranium One Group in potential scope for Western utility channels.The Wild Card — Westinghouse $50B+ IPO Pre-Filing Window: Bloomberg’s report that Westinghouse Electric is targeting a $50+ billion valuation with SEC confidential draft filings active since July 31. At $50 billion enterprise value, Cameco’s 49% stake equals ~$24.5 billion—nearly double CCJ's current market capitalization of ~$12–13 billion.Disclaimer This audio overview and accompanying text are produced for informational and educational purposes only and do not constitute financial, investment, legal, or tax advice. Uranium markets carry substantial risk. Always perform independent due diligence and consult a licensed financial advisor This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit uraniumunleashed.substack.com/subscribe

Episode OverviewThe story of the uranium market this week is not the spot price—it is the widening gap between what utilities pay to secure material four to five years forward and what traders bid for immediate supply. TradeTech’s long-term indicator printed at $97.00/lb, surpassing the previous long-term contract nominal peak of $95.00/lb set between May 2007 and March 2008. With spot lingering at $90.00/lb, the resulting -$7.00/lb spot discount underscores where institutional conviction currently sits. This episode breaks down the structural shift following the World Nuclear Symposium, Kazatomprom’s formalized supply posture, and Google’s landmark Finnish nuclear PPA.Weekly Market Snapshot (As of Sept 18, 2026)TradeTech Weekly Spot Indicator: $90.00/lb (+$0.25 WoW)TradeTech Mid-Term Indicator: $91.00/lbTradeTech Long-Term Indicator: $97.00/lb (Exceeds May 2007–March 2008 peak of $95.00/lb)Spot YTD Performance (2026): +9.8%Spot YoY Performance: +20.8%Spot–Term Spread: -$7.00/lb (Spot trades at a $7.00 discount to term)Producer Active Discussion Range: Above $100.00/lb for delivery extending through 2030Key Takeaways & Core Stories1. Long-Term Contract Price Breaks 2007 Peak ($97/lb)TradeTech’s long-term contract indicator reached $97.00/lb, moving past the historical nominal contract peak of $95.00/lb.Historical Precision: In 2007, the spot market spiked to approximately $137.00/lb due to short-term speculation and inventory hoarding, while long-term contracts never exceeded $95.00/lb. In the current cycle, term pricing leads spot, reflecting utility-driven, bilateral contract negotiations for five-year forward delivery.2. Kazatomprom’s Price-Insensitive Supply PostureKazatomprom has formalized its "value over volume" strategy as a price-insensitive posture, confirming that incremental spot price increases will not bring back unscheduled Kazakh production.Subsoil & Guidance Clarification: The nominal Subsoil Use Agreement ceiling was revised to 29,697 tU (cut from 32,777 tU). Actual 2026 operational production guidance stands at 27,500–29,000 tU on a 100% basis and 14,500–15,500 tU on an attributable basis.3. Contracting Cycle Restart & Hyperscaler CapitalFollowing the conclusion of the World Nuclear Symposium in London on September 11, utilities re-entered contracting discussions with the operational assumption that Western fuel buyers are structurally under-contracted.Google / Fortum PPA (Signed Sept 9): A 22-year PPA for up to 50% of the output of the Loviisa nuclear plant (2030–2049). The revenue guarantee underwrites Fortum’s ~€1 billion investment to extend Loviisa’s license to 2050, backed by Google’s ≥€13 billion infrastructure commitment in Finnish data centers across 2027–2028.Market Data & EquitiesSpot-Term Dynamics: Spot at $90.00/lb re-tested technical support, while the term market established a firm $7.00/lb premium.Equity Performance: The market continues to reward producers holding uncontracted inventory. Developer names with Athabasca Basin exposure—including NexGen and Denison—maintained weekly gains alongside constructive performance in Sprott Physical Uranium Trust (SPUT) and North American producer equities.The Week’s Defining SignalThe -$7.00/lb spot discount relative to long-term contract pricing represents a rare tightness regime. Because term pricing is locked into non-renegotiable bilateral utility contracts negotiated post-Symposium, spot prices are expected to compress upward into term over time as inventory holders demand higher prices to part with material.Three Things to Watch Next WeekPost-Symposium Utility RFPs: Watching for late-September utility RFP responses settling at or above $100.00/lb.Kazatomprom Q3 Operational Update: Tracking any further clarification on production targets and supply availability.U.S. Enrichment & HALEU Milestones: Monitoring developments in the U.S. Department of Energy’s $2.7 billion enrichment program and permitting progress for domestic conversion facilities.Mandatory DisclosureThis podcast and show notes are produced for informational and educational purposes only. Nothing herein constitutes financial, investment, legal, or tax advice. Uranium markets involve significant risk, including potential loss of principal. The views expressed do not constitute a recommendation to buy or sell any security. Always conduct your own due diligence and consult a licensed financial advisor before making investment decisions. This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit uraniumunleashed.substack.com/subscribe

Show NotesChina's nuclear construction program remains the world's largest and fastest-expanding power buildout. As of mid-September 2026, the country operates approximately 63 commercial power reactors (~64 GWe total capacity) with another 38 to 40 large-scale units under construction across more than a dozen sites. Under the 15th Five-Year Plan approved in March 2026, Beijing targets 110 GWe of installed capacity by 2030, backed by an estimated $80 billion in nuclear investment for 2026 and a steady approval cadence of roughly ten reactors per year.Key Weekly Highlights & Fleet MilestonesZhaoyuan-2 First Concrete: Safety-related concrete was poured for the nuclear island at Zhaoyuan-2 in Shandong on 5 September 2026. The pour involved ~8,800 cubic meters over 60 hours for the 1,117 MWe Hualong One unit, marking the second reactor at CGN's new six-unit site.State Council Approval of 8 Reactors: On 31 July 2026, Premier Li Qiang chaired the approval of eight new units: Jinqimen 3–4 and Taipingling 5–6 (designated as Hualong One 2.0 demonstration projects), Zhuanghe 1–2 (Hualong One), and Laiyang 1–2 (marking the first standardized batch-built deployment of the CAP1400/Guohe One design).Commercial Operations Achieved: Both Taipingling-2 (1,116 MWe Hualong One in Guangdong) and Changjiang-3 (Hualong One in Hainan) completed final commissioning and entered commercial operation on 3 August 2026.Hot Functional Testing Completed: Haiyang-3 (1,161 MWe CAP1000 in Shandong) completed hot testing on 13 August 2026 ahead of grid connection expected in 2026. Russian-supplied Xudabao-3 (VVER-1200 in Liaoning) completed hot testing on 2 June 2026.Major Civil Engineering Milestones: Xudabao-1 (CAP1000) hoisted its 1,000-tonne, 41-meter outer containment dome in August 2026 in under three years from initial licensing. Bailong-2 (CAP1000 in Guangxi) poured first safety concrete in August 2026.Technology & Pipeline DiversityChina’s reactor portfolio spans multiple technology generations:Generation III / III+: Hualong One (HPR1000) and the upgraded Hualong One 2.0, localized AP1000s (CAP1000), CAP1400 (Guohe One) batch deployment at Laiyang, Russian VVER-1200 units at Xudabao, and French EPR units at Taishan.Generation IV Demonstrations: Operational HTR-PM (210 MWe high-temperature gas-cooled reactor) at Shidaowan and twin CFR-600 sodium-cooled fast-neutron demonstration reactors under construction at Xiapu.Small Modular Reactors (SMRs): The ACP100 (Linglong One) 125 MWe multi-purpose PWR demonstration at Changjiang.Long-Term Capacity Roadmap2025 (Baseline): ~62 GWe.2030 (15th Five-Year Plan Target): 110 GWe.2035 Target: 200 GWe.2050 Long-Range Target: ~335 GWe.DisclaimerThis update is for informational and educational purposes only and does not constitute investment advice, a solicitation to buy or sell securities, or a financial recommendation regarding any energy company or uranium producer This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit uraniumunleashed.substack.com/subscribe

Show NotesOverview & Episode Summary Uranium closed last week at $90/lb—its highest level in nearly two years—following the World Nuclear Association (WNA) Symposium in London. With the conference delegates heading home, the market faces a critical test week to determine whether $90 represents a durable price floor or a temporary conference bounce.Hard Calendar — Confirmed CatalystsThursday, September 17 — Uranium Royalty Corp (UROY) Q1 FY2027 Earnings Call (7:00 AM ET):Management faces analysts for the first time since closing the $1.1 billion Sweetwater Royalties acquisition. While analysts are modeling ~$156.5 million in revenue, the key focus is whether leadership provides full-year pro-forma guidance and updates on near-term cash-generating assets like the South Texas Project. Clear guidance could trigger a equity re-rating above UROY's current sum-of-parts discount.Friday, September 18 — TradeTech Weekly Spot Price Indicator: Published at the end of the business day, this print provides the first read on post-conference price sustainability. A Friday close above $90 in a quiet week opens the path toward the $93–$95 resistance level from the 2024 peak. A pullback below $89 indicates the market needs earnings season catalysts to sustain current levels.Expected Developments to WatchBannerman Energy–CNNC JV Finalization: Following the September 9 confirmation that all conditions precedent were satisfied, Bannerman Energy (ASX: BMN) could formally complete its $321.5 million share subscription and shareholders agreements with CNNC at any point. Formal closing starts the clock on a Q4 2026 Final Investment Decision (FID) for the Etango project in Namibia.WNA Symposium Contracting Announcements: After the WNA highlighted a 550 GW pledged capacity gap without corresponding projects under construction, utility contracting discussions are expected to transition into public offtake agreements. Disclosed term contracts at or above $95/lb would validate current long-term pricing indicators.Westinghouse Public S-1 Watch: Following its confidential draft submission on July 31, 2026, Westinghouse Electric (49% owned by Cameco) is in a prime window to publicly file its Form S-1 on SEC EDGAR. A public filing will convert an estimated $3.9B–$5.9B in embedded value on Cameco's balance sheet into a transactable market valuation.Developing Stories & Geopolitical RiskNiger–Orano Shipment Breach: Niger's military government exported ~1,000 tonnes (~2.6 million lbs) of SOMAÏR uranium in direct breach of the ICSID Arbitral Tribunal’s provisional measures order, creating a live case study in resource nationalism for sovereign-risk jurisdictions.Kazatomprom (KAP) EGM Approaching: Absentee voting opens September 22 ahead of the October 7 vote to ratify major long-term supply agreements with China's SNURDC and Russia's Uranium One This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit uraniumunleashed.substack.com/subscribe
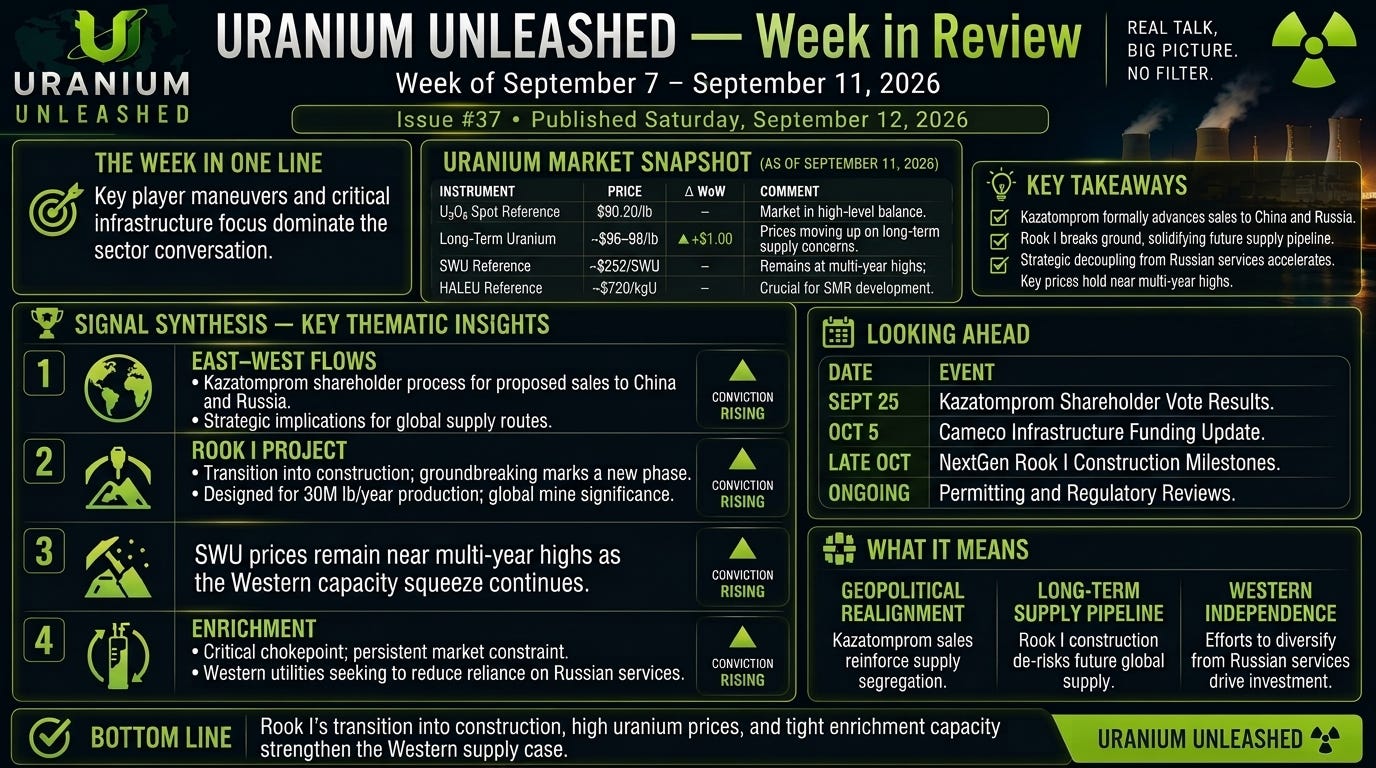
This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit uraniumunleashed.substack.com/subscribe

Comments

Download from Google Play

Download from App Store
 United States